
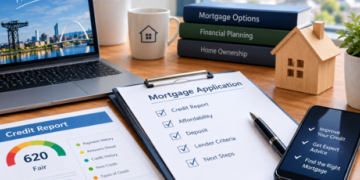

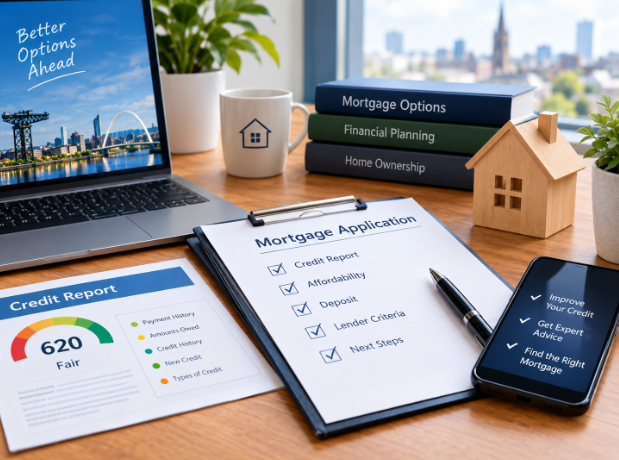
Previous credit problems do not always mean that home ownership is impossible, but they can affect which mortgage lenders may consider an application. The useful starting point is to understand the type, age and status of the credit issue, then look at affordability, deposit and current financial behaviour.
Not all credit problems are the same
An old satisfied default can be treated differently from recent missed payments, active arrears or multiple adverse accounts. The amount involved, date and current status can all matter. A credit score shown by a reporting service is only one part of the picture. Reviewing the underlying entries gives a clearer basis for mortgage planning.
Check your credit reports
Before applying, obtain your credit reports and check the information carefully. If there is an error, use the appropriate process to challenge it. Keep evidence showing when accounts were settled where relevant. Understanding the exact history allows a mortgage adviser to consider lender criteria more accurately.
Deposit and affordability still matter
A larger deposit can improve the loan-to-value position, but it does not automatically remove the effect of adverse credit. Lenders still assess affordability and payment history. Buyers should avoid using every available saving as a deposit if doing so leaves no emergency reserve. The source of the deposit may also need to be evidenced.
Recent financial behaviour is important
Maintaining current commitments and avoiding unnecessary new borrowing can help create a clearer recent financial record. If the adverse event is old and recent payments have been maintained, the case may look different from an application with ongoing missed payments. There is no guaranteed outcome, but current behaviour forms part of the wider assessment.
Timing can change the options
In some circumstances, waiting allows adverse events to become older and creates a longer record of stable payments. However, waiting is not automatically necessary. The right timing depends on the property, deposit, affordability and lender criteria. Avoid making repeated applications without understanding why a previous application may not have fitted.
Explain unusual circumstances honestly
If a credit problem was connected to a specific event, provide a factual explanation and supporting evidence where appropriate. Explanations do not override lender rules, but they can help an adviser understand the case. Never omit information simply because it may appear less attractive.
Avoid guaranteed-approval claims
Borrowers with adverse credit can be vulnerable to claims that a particular lender or broker can guarantee approval. A responsible mortgage process still involves affordability assessment and lender underwriting. Be cautious about paying for services that promise a guaranteed mortgage outcome.
Specialist mortgage advice
Prestige Mortgage Solutions Ltd can help borrowers understand how lender criteria may apply to their current circumstances. The aim is to identify realistic routes and prepare an accurate application rather than promise approval. If a borrower is experiencing serious ongoing financial difficulty, independent debt advice may be appropriate before securing debt against a home.
Prepare a factual explanation
If a credit problem was caused by redundancy, illness, a dispute or another documented event, prepare a concise factual explanation and supporting evidence where appropriate. Do not exaggerate or conceal anything. The lender will make its own assessment, but clear information helps the application be understood.
Consider independent debt advice where appropriate
If missed payments and arrears are ongoing, obtaining a mortgage may not be the immediate priority. Independent debt advice can help establish whether the household’s finances are sustainable. Securing existing debt against a property without addressing the underlying problem can increase risk. Mortgage advice and debt advice can serve different purposes.
Be cautious about credit repair promises
There are services that advertise rapid improvements or guaranteed mortgage approval. Be careful with any claim that suggests a lender decision can be guaranteed. Credit information should be corrected when it is inaccurate, but legitimate improvement generally comes from accurate records and responsible financial behaviour rather than shortcuts.
Protect the deposit reserve
Applicants with adverse credit may feel pressure to use every saving to improve the deposit. A larger deposit can be useful, but keeping an emergency reserve remains important. Home ownership creates costs that cannot always be predicted. A mortgage that leaves the borrower with no savings can become difficult to manage if an unexpected repair or income change occurs.
Avoid applying without understanding the credit timeline
Before a mortgage application, map out when each adverse event occurred, whether it has been satisfied and whether any accounts remain active. This timeline can help an adviser understand the case. It is much more useful than simply saying that you have ‘bad credit‘. The details determine which lender criteria may be relevant.
Keep your application factual
A straightforward explanation of the financial history is usually more useful than trying to make the application sound perfect. Provide accurate dates, amounts and supporting documents. The lender will make its own decision, but a well-organised application helps the relevant facts remain clear.
Budget for higher costs where applicable
Specialist mortgage options can have different pricing or fees from mainstream products. If your circumstances mean fewer lenders are available, compare the full cost carefully. The monthly payment should remain affordable, and you should understand what happens when the initial deal ends.
Think about the property as well as the borrower
Even when the borrower’s credit history is acceptable to a specialist lender, the property still needs to meet the lender’s criteria. Unusual construction, certain property types or valuation issues can affect mortgageability. Do not assume that solving the credit side automatically solves the whole application.
Keep settlement evidence
If a default or other adverse account has been paid, keep confirmation showing the date and status. This can be useful if a lender requests evidence. Make sure your credit files also show the correct current status where possible. Accurate records make the application easier to understand.
Avoid unnecessary new borrowing before applying
If you are preparing for a mortgage, avoid taking new credit simply because it is available. New borrowing can change affordability and may create additional questions. If a new loan is genuinely necessary, disclose it accurately. A mortgage application should reflect your real financial position, not an artificially simplified one.
Separate historic issues from current problems
A mortgage application involving historic adverse credit should distinguish between events that are fully resolved and issues that are still active. A satisfied account with a long clean payment history can present a different picture from current arrears. This distinction does not guarantee acceptance, but it helps an adviser understand which lender criteria may be relevant.
Keep expectations realistic
There is no universal mortgage product for every credit history. Some cases may have fewer options, higher costs or require more time before an application is sensible. A clear understanding of these possibilities helps borrowers make informed decisions. Where home ownership is not immediately achievable, improving the financial position can sometimes widen the future options.
Review the position before each application
Credit circumstances can change between applications. A new loan, missed payment, change in employment or increase in savings may affect the available options. If an application is declined, understand the reason before immediately applying elsewhere. A carefully planned next step can be more useful than multiple applications made without knowing which criteria did not fit.
Consider the whole household budget
A specialist mortgage should still fit the household’s wider budget. Include utilities, council tax, insurance, transport, maintenance and ordinary living costs when assessing the payment. If the mortgage is only affordable by cutting essential spending, the application may not be sustainable even if a lender is willing to proceed. The purpose of specialist advice is to identify realistic options, not to encourage a borrower to stretch beyond their means.
Frequently Asked Questions
Can I get a mortgage with a default?
Possibly. The effect of a default depends on factors including its age, amount, status, deposit and lender criteria.
Does a higher deposit help with adverse credit?
It can improve the loan-to-value position, but it does not automatically overcome credit issues or affordability concerns.
Should I wait before applying?
Sometimes waiting can improve a credit profile, but the right timing depends on the specific circumstances and lender criteria.
Can a broker guarantee approval?
No responsible adviser can guarantee a lender’s final decision. The lender makes its own underwriting assessment.
What if my credit report contains an error?
Investigate the error with the relevant credit reference agency or creditor and keep evidence of any correction.
Conclusion
Mortgage decisions are easier to manage when the full financial picture is understood before an application is made. For readers considering bad credit mortgage Glasgow, preparation should focus on genuine affordability, lender criteria, property information and the long-term cost of the borrowing. Professional advice can help explain the available routes, but the final decision should always reflect the borrower’s own circumstances and the terms of the mortgage offered.